Loading
Last discussed
2y ago
Feb 27, 2024
0 tagged in 12 months
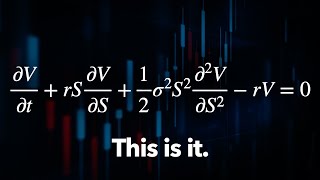
The Equation That Beat Wall Street
Veritasium·Feb 27, 2024
All time
1
episodes
On record
1
took a position
Where they standWhere they stand
Talking pointsNot enough disagreement in the transcripts to form camps. These are the positions taken by people with demonstrated expertise on this topic first, then by how many people heard them on it, then by VoiceRank. Positions are extracted from transcripts by a model and may misattribute who said what. Every quote links to the episode it came from.

The Black-Scholes formula became an essential benchmark for Wall Street due to providing an explicit mathematical expression for option pricing.
“Well, because when you solve that partial differential equation, you get an explicit formula of the price of the option as a function of a bunch of these input parameters. And for the very first time, you now have an explicit expression where you plug in the parameters and out pops this number”
Veritasium · Feb 2024 · 1 episode · 17.5M views on this topicExtracted by a model; may misattribute who said what.
In the transcripts